Paper Menu >>
Journal Menu >>
 Open Journal of Statistics, 2012, 2, 297-299 http://dx.doi.org/10.4236/ojs.2012.23035 Published Online July 2012 (http://www.SciRP.org/journal/ojs) Unbalanced Regressions and Spurious Inference Daniel Ventosa-Santaulària Centro de Investigación y Docencia Económicas, CIDE, Mexico City, Mexico Email: [email protected] Received April 23, 2012; revised May 24, 2012; accepted June 5, 2012 ABSTRACT Spurious regression has been extensively studied in time series econometrics since Granger and Newbold’s [1] seminal paper. Recently, it has been advanced that this phenomenon is due to a mistreatment of short-range autocorrelation in the residuals of the regression when at least one of the variables in a bivariate regression is stationary. HAC errors, fea- sible GLS and Cochrane-Orcutt-type procedures are then proposed to draw correct inference. Such a proposal should be cautiously considered, since nonsense inference might also be due to deterministic trend mechanisms, structural breaks, and long range dependence. In these cases, standard autocorrelation correction procedures would not solve the problem of spurious regression. We aim to make the later argument clear. Keywords: Spurious Regression; Stationarity; Unbalanced Regression; Unit Root 1. Unbalanced Spurious Regressions Spurious regression has been extensively studied since Granger and Newbold [1] seminal paper in which inde- pendent nonstationary variables are simulated and then used to estimate a simple bivariate regression. Phillips [2] provided the theoretical framework to understand the phenomenon in the simplest case (independent driftless unit root processes). Since then, the spurious regression phenomenon has been identified for many data-generat- ing processes (DGPs), such as unit root with drifts, (bro- ken-) trend stationary and long range, for example1. Here, we are concerned with the results presented in Noriega and Ventosa-Santaulària [4] and Stewart [5] pertaining to the spurious regression phenomenon under the following conditions: 1) both variables, t and t y x (see Equation (1)), are stationary (i.e., integrated of order 0, I(0)), and 2) at least one of the variables (the regressor or the regressand) is integrated of order 1, I(1). The later combinations result in an unbalanced regression and Noriega and Ventosa-Santaulària [4] found that, in a sim- ple regression specification, , ttt yxu t y (1) where either , t x (or both) is I(0)2, the t-ratio associ- ated with ˆ , ˆ t , does not diverge as the sample size grows; i.e. . Results in Noriega and Ventosa- Santaulària [4] imply that the asymptotic spurious re- gression phenomenon does not occur. Nevertheless, non- sense inference cannot be fully discarded. In a recent paper, Stewart [5] argues that, although the t-ratio does not diverge, it may not necessarily converge to a standard normal distribution. Furthermore, in the absence of auto- correlation in the DGP’s innovations, only when both variables are iid I(0) processes, the t-ratio behaves— asymptotically—as a standard normal. Other DGP com- binations, such as ~1 tI ~1 − t y x I and vice versa, do have asymptotic nonstandard distributed t-ratios. Nev- ertheless, the size distortions are better explained by the presence of autocorrelation in the DGP innovations. This point is illustrated by Stewart [5] throughout a number of finite-sample experiments. The problem comes as no surprise since the estimated residuals behave as an auto- correlated process and size distortion should be expected in that case. Moreover, the use of heteroskedasticity and autocorrelation consistent (HAC) errors considerably re- duce size distortions in some cases, as argues Stewart [5]. Table 1 summarizes the relevant DGPs for both the de- pendent and the explanatory variables, similar to those used by Noriega and VentosaSantaulària [4] and Stewart [5], to estimate a simple linear specification. For simplicity, we assume that innovations, z t, for e ,zx y , are iid white noises. Following Noriega and Ventosa-Santaulària [4] and using the aforementioned DGPs, we present the following corollary: ˆ1 p tO Corollary Let t and 1For a recent survey see Ventosa-Santaulària [3]. yt x , be generated by DGPs i and j of Table 1. Denote ij as the DGP combination that generated y and x, respectively, and use them to 2In Noriega and Ventosa-Santaulària [4], the other variable may be- have as: 1) driftless I(1); 2) I(1) with drift (with a possible drift break); 3) I(2); and 4) (Broken-)Trend stationary. C C opyright © 2012 SciRes. OJS 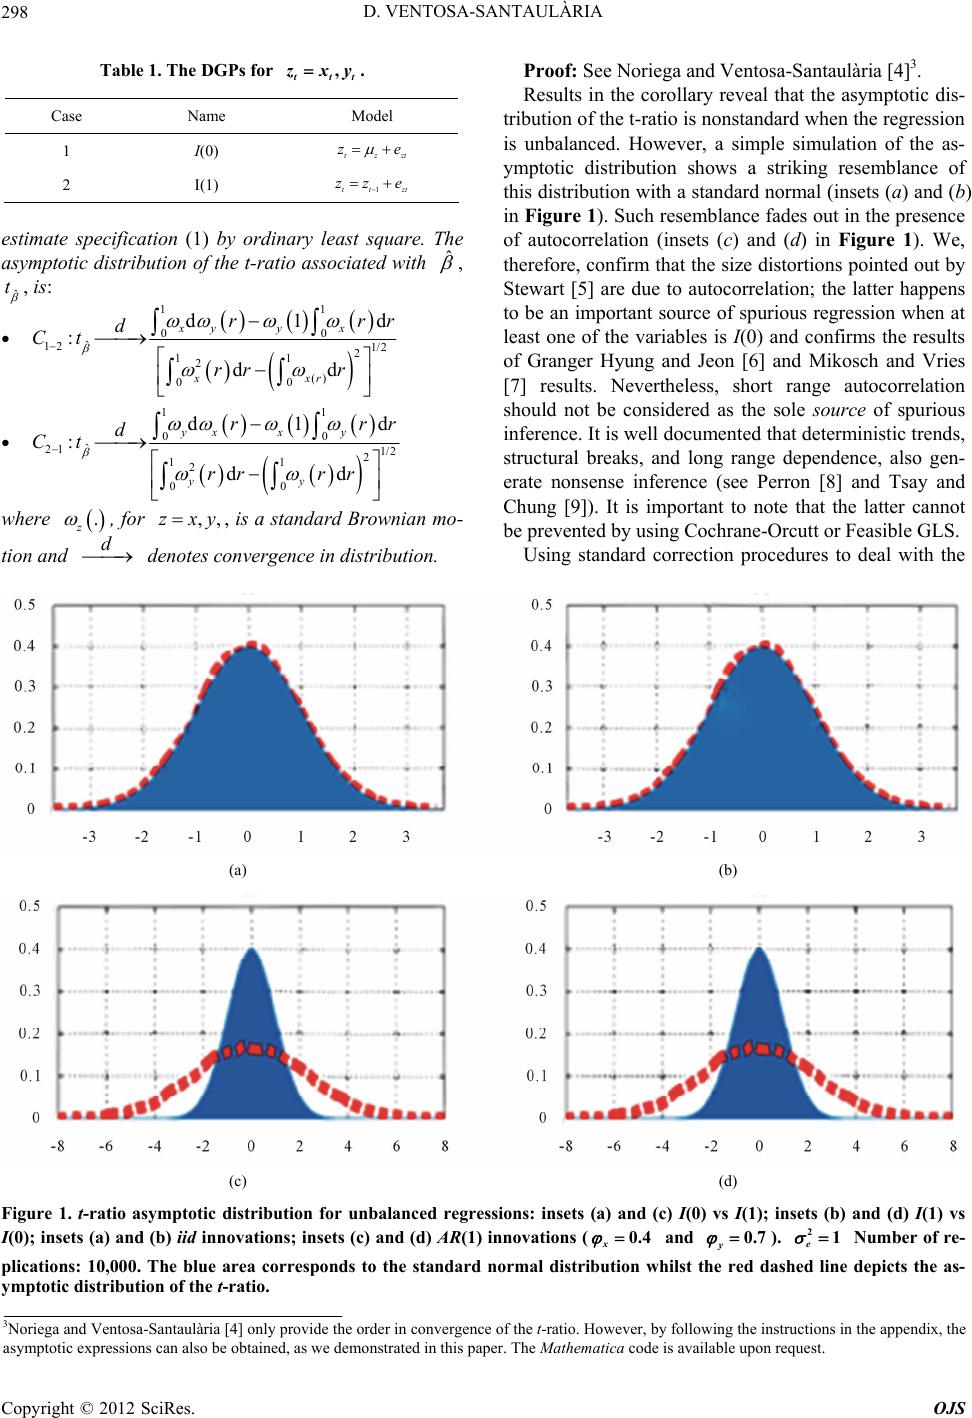 D. VENTOSA-SANTAULÀRIA 298 Table 1. The DGPs for , ttt zx y . Case Name Model 1 I(0) tzz ze t 2 )1(I 1tt zt zz e estimate specification (1) by ordinary least square. The asymptotic distribution of the t-ratio associated with ˆ , ˆ, is: t 11 00 12 1/ 2 11 0 ˆ 2 () 0 d1d : dd xy y xxr rrr Ct r d rr 2 x 11 00 11 2 00 ˆ d1d dd :yx x yy rrr Ct rr rr d ,,zxy 21 1/2 2 y where , for , is a standard Brownian mo- . z d tion and Proof: See Noriega and Ventosa-Santaulària [4]3. Results in the corollary reveal that the asymptotic dis- tribution of the t-ratio is nonstandard when the regression is unbalanced. However, a simple simulation of the as- ymptotic distribution shows a striking resemblance of this distribution with a standard normal (insets (a) and (b) in Figure 1). Such resemblance fades out in the presence of autocorrelation (insets (c) and (d) in Figure 1). We, therefore, confirm that the size distortions pointed out by Stewart [5] are due to autocorrelation; the latter happens to be an important source of spurious regression when at least one of the variables is I(0) and confirms the results of Granger Hyung and Jeon [6] and Mikosch and Vries [7] results. Nevertheless, short range autocorrelation should not be considered as the sole source of spurious inference. It is well documented that deterministic trends, structural breaks, and long range dependence, also gen- erate nonsense inference (see Perron [8] and Tsay and Chung [9]). It is important to note that the latter cannot be prevented by using Cochrane-Orcutt or Feasible GLS. Using standard correction procedures to deal with the denotes convergence in distribution. (a) (b) (c) (d) Figure 1. t-ratio asymptotic distribution for unbalanced regressions: insets (a) and (c) I(0) vs I(1); insets (b) and (d) I(1) vs I(0); insets (a) and (b) iid innovations; insets (c) and (d) AR(1) innovations ( and 0.4 x 0.7 y ). Number of re- plications: 10,000. The blue area corresponds to the standard normal distribution whilst the red dashed line depicts the as- mptotic distribution of the t-ratio. 21 e y 3Noriega and Ventosa-Santaulària [4] only provide the order in convergence of the t-ratio. However, by following the instructions in the appendix, the asymptotic expressions can also be obtained, as we demonstrated in this paper. The Mathematica code is available upon request. Copyright © 2012 SciRes. OJS  D. VENTOSA-SANTAULÀRIA 299 spurious regression phenomenon is tempting, even if such procedures cannot always provide correct inference (see Stewart [5] and McCallum [10], for example). Sun [11] proposed a convergent t-statistic using modified HAC errors with a bandwidth proportional to the sample size when the variables are highly persistent. The author ac- knowledges, however, that such a procedure cannot be used in empirical applications, since the limit distribution of the test depends on the memory parameter under the null hypothesis and critical values cannot, therefore, be tabulated. McCallum [10] and Kolev [12] also advocate classical correction procedures to deal with spurious re- gressions, such as the Cochrane-Orcutt procedure and Feasible Generalized Least Squares. They argue that us- ing them reduces size distortions of the t-test. However, Martínez-Rivera and Ventosa-Santaulària [13] proved that such methods are not always effective and remain highly dependent on the DGP of the series4. 2. Concluding Remarks There is finite-sample evidence showing that spurious inference in unbalanced regressions mostly occurs when the innovations of the DGPs are not iid. In that sense, standard autocorrelation-correction procedures, such as HAC errors, Feasible GLS and Cochrane-Orcutt esti- mates, have been advanced to eliminate/reduce the size distortions and, thus, spurious inference. This approach should, nevertheless, be reconsidered. First, there is evi- dence that spurious regression using stationary series cannot always be interpreted as a short range autocorre- lation phenomenon: long range dependence and struc- tural breaks (level shifts, for example) also cause spuri- ous inference; spurious regression cannot, therefore, be always corrected using classical procedures. Second, an unbalanced regression (in which the order of integrations of the involved series is not the same) is an empirical situation which remains to be proved relevant. The esti- mation of an unbalanced regression is not intuitive, al- though there are cases such as in the predictive equation in the finance literature, in which the market returns (usually, found to be stationary) is regressed against dividend yield (stationary but highly persistent). Spurious regression cannot be simply considered as a short-mem- ory autocorrelation phenomenon and cannot, therefore, be treated using standard procedures. The main conclu- sion is, therefore, twofold: 1) practitioners should inter- pret cautiously their results whenever they find evidence of autocorrelation, since the inference could be spurious; 2) they should, however, be aware that spurious regres- sions arise for many diverse reasons, autocorrelation be- ing only one of them; standard autocorrelation correction procedures are not to be considered as the sole solution to prevent spurious inference; on the contrary: parameter stability, long memory and cointegration tests should always be also considered. REFERENCES [1] C. W. J. Granger and P. Newbold, “Spurious Regressions in Econometrics,” Journal of Econometrics, Vol. 2 No. 2, 1974, pp. 111-120. doi:10.1016/0304-4076(74)90034-7 [2] P. C. B. Phillips, “Understanding Spurious Regressions in Econometrics,” Journal of Econometrics, Vol. 33, No. 3, 1986, pp. 311-340. doi:10.1016/0304-4076(86)90001-1 [3] D. Ventosa-Santaulària, “Spurious Regression,” Journal of Probability and Statistics, Vol. 2009, No. 1, 2009, pp. 155-182. doi:10.1155/2009/802975 [4] A. E. Noriega and D. Ventosa-Santaulària, “Spurious Re- gression and Trending Variables,” Oxford Bulletin of Economics and Statistics, Vol. 69, No. 3, 2007, pp. 439- 444. doi:10.1111/j.1468-0084.2007.00481.x [5] C. Stewart, “A Note on Spurious Significance in Regres- sions Involving I(0) and I(1) Variables,” Empirical Eco- nomics, Vol. 41, No. 3, 2011, pp. 565-571. doi:10.1007/s00181-010-0404-5 [6] C. W. J. Granger IV, N. Hyung and Y. Jeon, “Spurious Regressions with Stationary Series,” Applied Economics, Vol. 33, No. 7, 2001, pp. 899-904. [7] T. Mikosch and C. G. Vries, “Tail Probabilities for Re- gression Estimators,” Tinbergen Institute Discussion Pa- pers, TI 2006-085/2, 2006. [8] P. Perron, “The Great Crash, the Oil Price Shock, and the Unit Root Hypothesis,” Econometrica, Vol. 57, No. 6, 1989, pp. 1631-1401. doi:10.2307/1913712 [9] W. J. Tsay and C. F. Chung, “The Spurious Regression of Fractionally Integrated Processes,” Journal of Economet- rics, Vol. 96, No. 1, 2000, pp. 155-182. doi:10.1016/S0304-4076(99)00056-1 [10] B. T. McCallum, “Is the Spurious Regression Problem Spurious?” Economics Letters, Vol. 107, No. 3, 2010, pp. 321-323. doi:10.1016/j.econlet.2010.02.004 [11] Y. Sun, “A Convergent T-Statistic in Spurious Regres- sions,” Econometric Theory, Vol. 20, No. 5, 2004, pp. 943-962. doi:10.1017/S0266466604205072 [12] G. I. Kolev, “The ‘Spurious Regression Problem’ in the Classical Regression Model Framework,” Economics Bulletin, Vol. 31, No. 1, 2011, pp. 925-937. 4There are other approaches worth mentioning. In Davidson and Mac- Kinnon [14], for example, the authors consider that the spurious re- gression phenomenon is, at least partially due to a misspecification o f the model. The authors argue that instead of Equation (1), practitioners should estimate yt = α + βxt + γyt-1 + μy. Using this specification makes the null hypothesis of the t-test valid. Simulations presented in David- son and MacKinnon [14] reveal, however, that even a correct specifi- cation is unable to provide an adequate size of the t-test under the null hypothesis when the variables are nonstationary. [13] B. Martínez-Rivera and D. Ventosa-Santaulària, “A Com- ment on ‘Is the Spurious Regression Problem Spurious?’” Economics Letters, Vol. 115, No. 2, 2012, pp. 229-231. [14] D. Davidson and J. G. MacKinnon, “Econometric Theory and Methods,” Oxford University Press, New York, 2004. Copyright © 2012 SciRes. OJS |